Brands
Marico expects Q2 FY27 revenue to grow in double digits, profit in mid-twenties
Parachute and value-added hair oils drive volume growth as India business stays strong

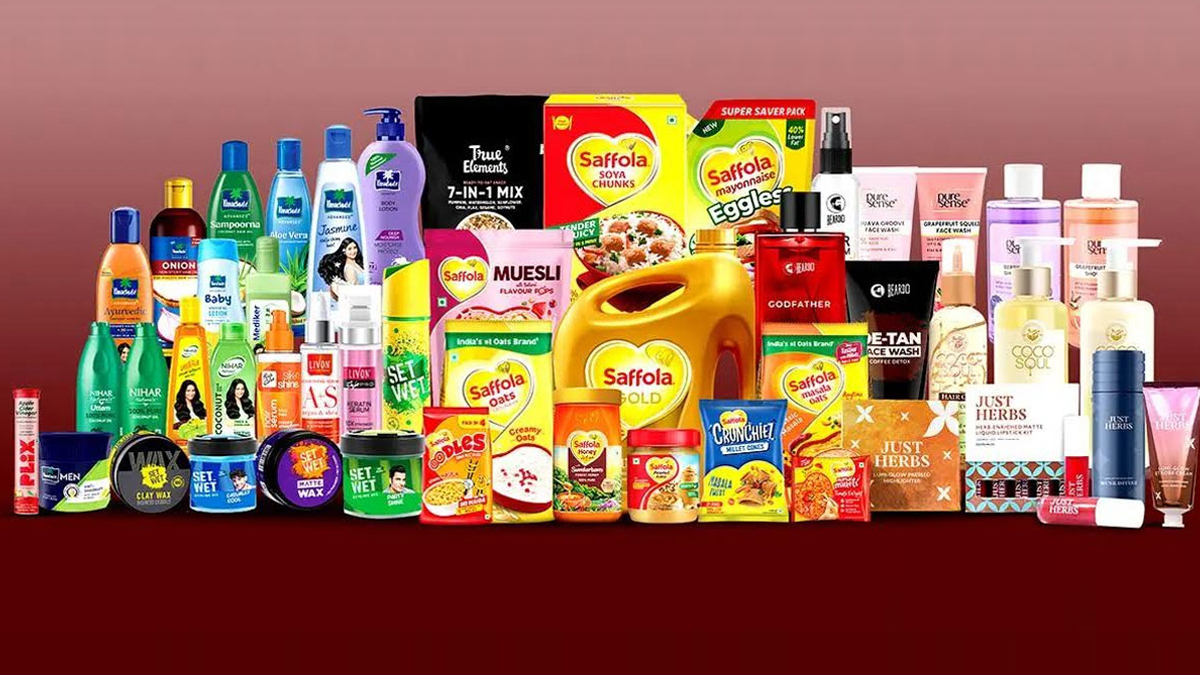
MUMBAI: Marico expects consolidated revenue to grow in double digits in the second quarter of FY27, while operating profit is likely to rise in the mid-twenties, as its core brands and newer growth businesses maintain momentum.
The consumer products company said domestic demand remained resilient during the quarter ended 30 September 2026, despite a volatile operating environment. Marico added that it remains optimistic about consumption trends while keeping a close watch on inflation.
The update is based on the company’s operating performance and demand trends for Q2 FY27. A detailed information update will be issued after the board approves the financial results.
Marico’s India business delivered another strong quarter, with underlying volume growth reaching double digits.
Parachute Coconut Oil recorded early-teens volume growth, accelerating from the previous period. The company attributed the performance to the brand’s equity and consumer trust, along with its supply chain capabilities.
Value Added Hair Oils recorded its sixth consecutive quarter of strong growth, with volume growth again reaching the twenties.
Marico said the performance reflects the strength of the franchise and a structural shift in its growth trajectory, supported by investments in mid and premium segments, greater direct reach through Project SETU and aggressive expansion of the Almond category.
Saffola Oils posted mid-single-digit price-led growth, although volumes declined as Marico focused on maintaining threshold profitability and rationalising the supply of select variants.
Foods and Premium Personal Care, including digital-first brands and shampoo, also maintained their growth momentum, supporting the company’s diversification strategy.
Marico’s international business delivered constant-currency growth in the teens during the quarter, led by strong performances in Vietnam, the Middle East and South Africa.
Bangladesh saw a marginal sequential improvement but continued to operate against a high base and persistently elevated inflation.
Overall, Marico expects consolidated revenue to grow in double digits, supported by its core portfolio, digital-first businesses and international operations.
On the input-cost front, Marico said crude-linked derivatives became more expensive during the quarter, while copra prices remained rangebound at around 35 per cent below their peak levels.
The company expects gross margin to accelerate strongly year on year, helped by a favourable portfolio mix and the benefit of lower copra prices.
At the same time, advertising and sales promotion investments increased significantly as Marico continued to spend on brand building and growth initiatives.
The company expects operating profit to grow in the mid-twenties.
With a strong first half of FY27, Marico said it is likely to surpass its near-term guidance across key financial parameters. The company attributed the outlook to sustained momentum in its core franchises and the scaling up of newer growth engines.
Marico said it remains focused on delivering sustainable and profitable volume-led growth over the medium term.