MAM
Kewal Kiran Clothing Q2 profit rises 15 per cent as revenue grows 5 per cent
H1 revenue climbs 11 per cent to Rs 652 crore, while EBITDA and net profit increase 19 per cent each

MUMBAI: The fashion business may have faced a few seasonal wrinkles, but Kewal Kiran Clothing Limited (KKCL) has managed to keep its numbers well pressed. The apparel company reported a 5 per cent year-on-year rise in revenue from operations to Rs 373 crore in the second quarter of FY27, while profit after tax (PAT) grew 15 per cent to Rs 54 crore.
The company’s earnings before interest, taxes, depreciation and amortisation (EBITDA) rose 12 per cent to Rs 80 crore during the quarter, compared with Rs 71 crore in the corresponding period last year. Its EBITDA margin improved to 21 per cent from 20 per cent, while PAT margin expanded to 14 per cent from 13 per cent.
Gross profit increased 7 per cent to Rs 160 crore from Rs 149 crore a year earlier. The gross profit margin also edged up to 43 per cent from 42 per cent, indicating an improvement in the margin alongside revenue growth.
The first half of FY27 offered a stronger picture. Revenue from operations rose 11 per cent to Rs 652 crore, against Rs 588 crore in H1 FY26. Gross profit grew 13 per cent to Rs 280 crore from Rs 248 crore, with the gross profit margin at 43 per cent compared with 42 per cent in the previous year.
EBITDA for the six-month period increased 19 per cent to Rs 133 crore from Rs 113 crore. The EBITDA margin stood at 20 per cent, up from 19 per cent. PAT also rose 19 per cent to Rs 94 crore, compared with Rs 79 crore in H1 FY26, while the PAT margin improved to 14 per cent from 13 per cent.
The quarter’s performance, however, came against a shift in the festive calendar. KKCL joint managing director Hemant Jain said Navratri and Durga Puja fell in October this year, compared with September last year, pushing some of the anticipated festive demand into the third quarter of FY27.
He described the quarter as resilient despite a challenging external environment, adding that the company remained focused on growth while maintaining profitability and operational discipline. Jain also pointed to the performance of Kraus, which, according to him, delivered robust sales growth alongside strong EBITDA margins.
The company’s focus, he said, remains on building a sustainable business with profitable growth. He added that KKCL’s balance sheet provides a foundation to navigate changing market conditions.
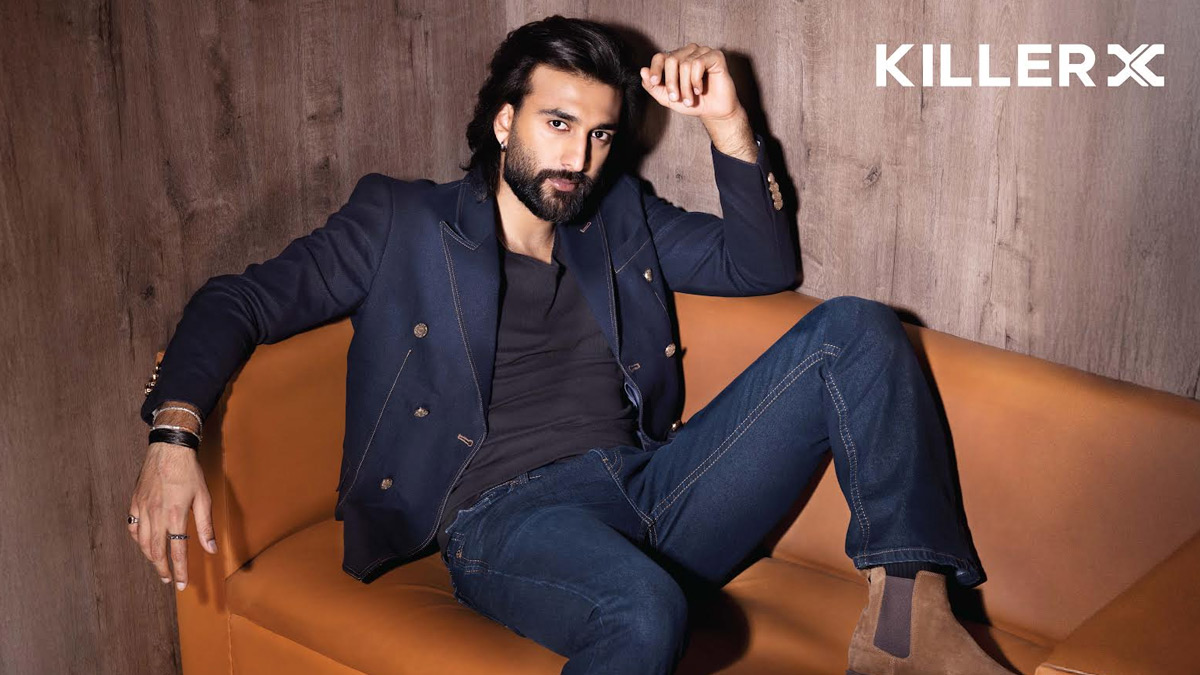
KKCL operates an integrated business spanning design, manufacturing, branding and retail, with a portfolio that includes Killer, Integriti, Lawman, Easies, Junior Killer and Kraus. The company has more than four decades of presence in India’s branded apparel market.
Its distribution network comprises 675 exclusive brand outlets and more than 80 distributors, covering over 3,000 multi-brand outlets across the country. It also has a presence in national chain stores.
For FY26, KKCL reported revenue from operations of Rs 1,123 crore, EBITDA of Rs 238 crore and PAT of Rs 153 crore. Its gross profit stood at Rs 511 crore, with gross profit, EBITDA and PAT margins at 42 per cent, 20 per cent and 12 per cent, respectively.
The latest results show that while the shift in festive demand weighed on the timing of some sales in Q2, the company maintained year-on-year growth across revenue, gross profit and profitability. The extent to which the deferred festive demand feeds into Q3 will be an important factor to watch in the coming quarter.